
 Phone
 Send Email
 whatsapp
 Facebook
 Youtube


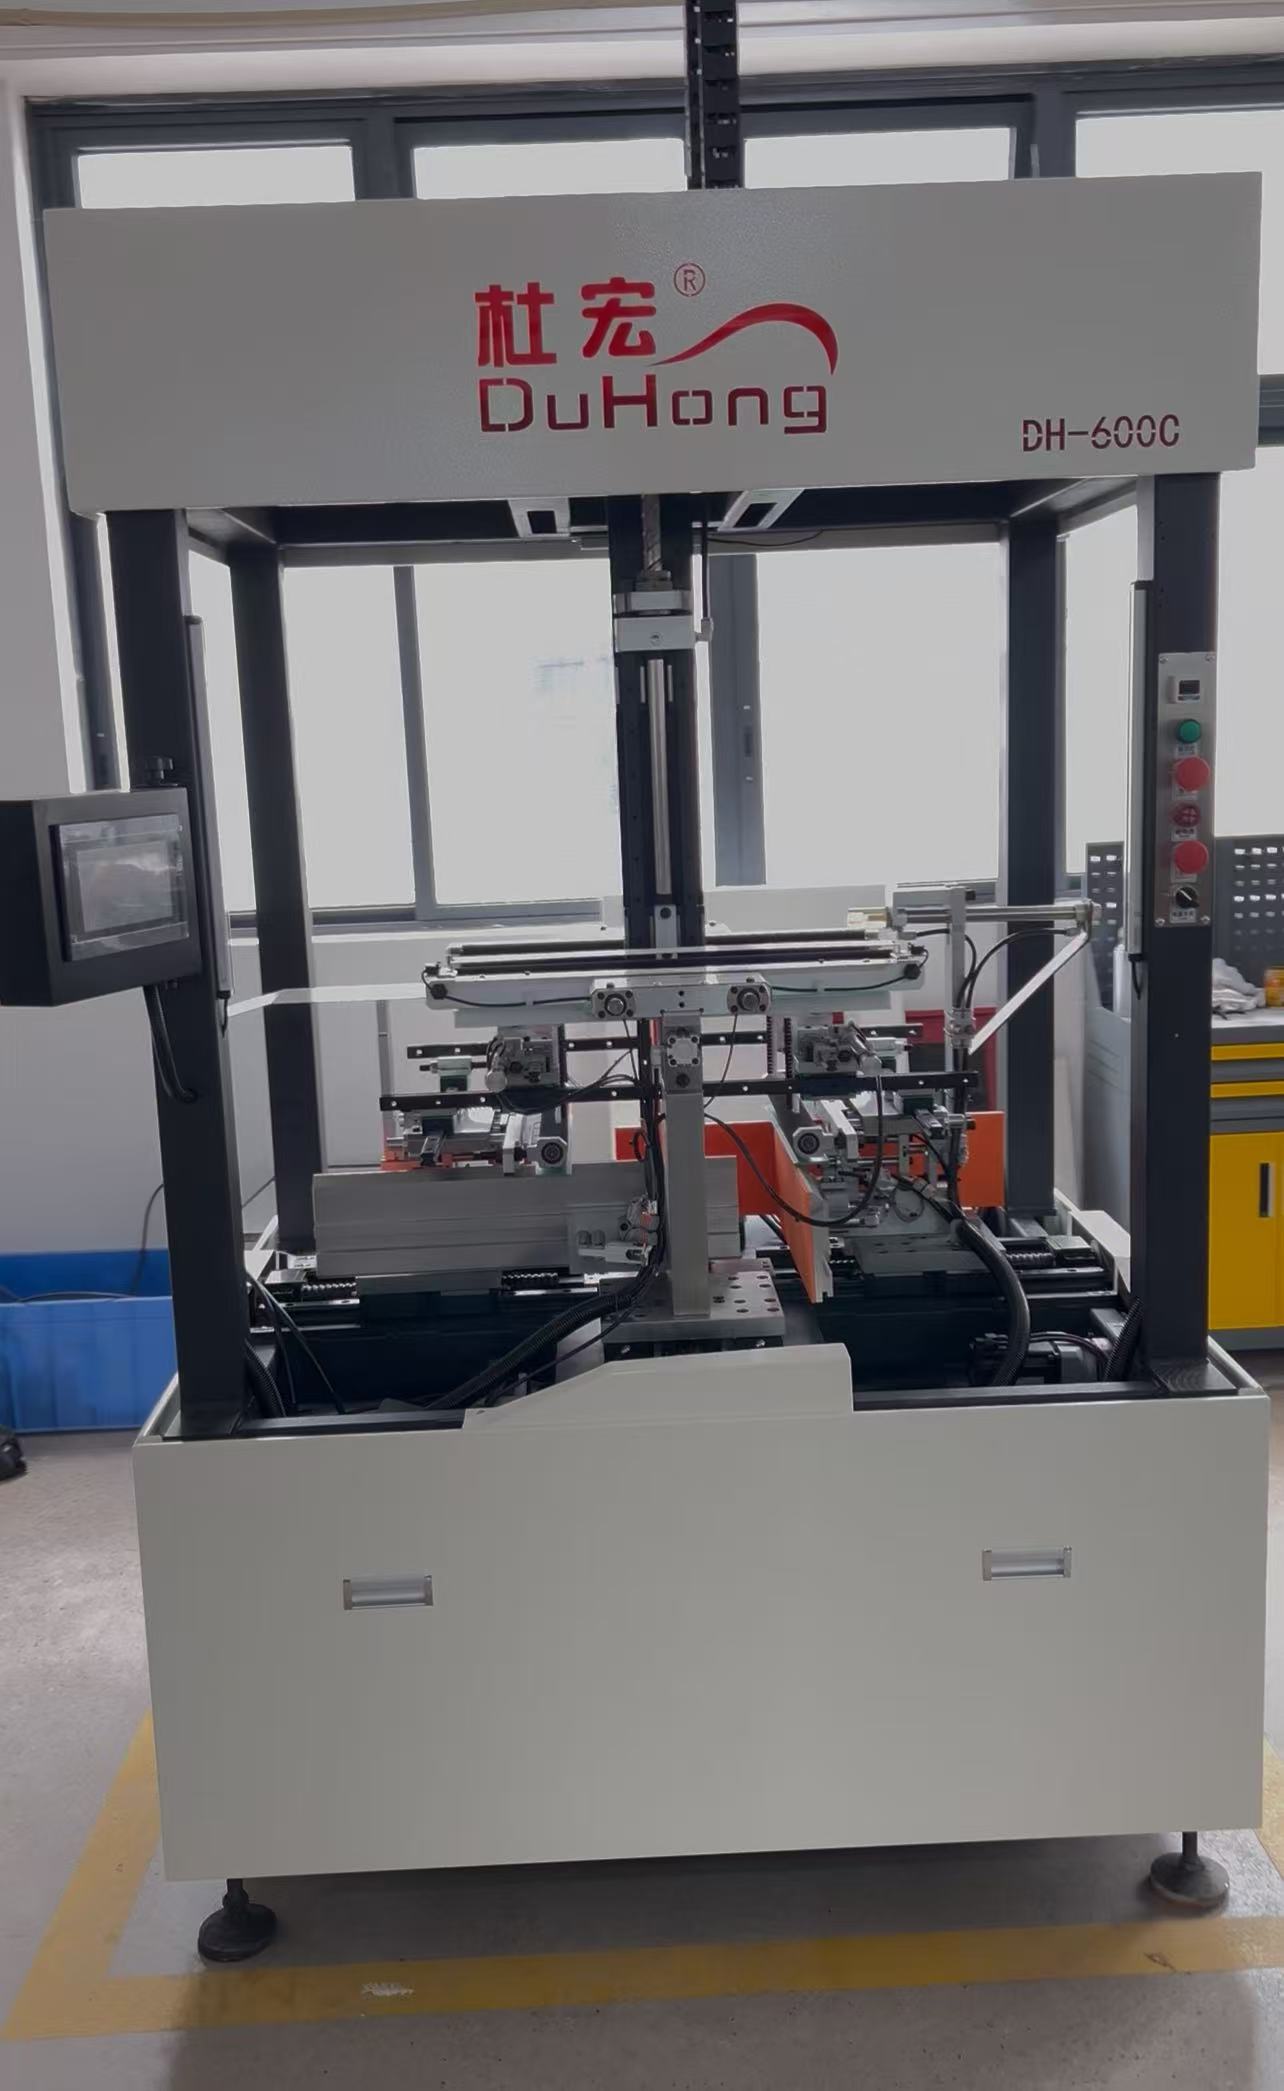


Development Report on the Global Automatic Rigid Box Making Equipment Industry
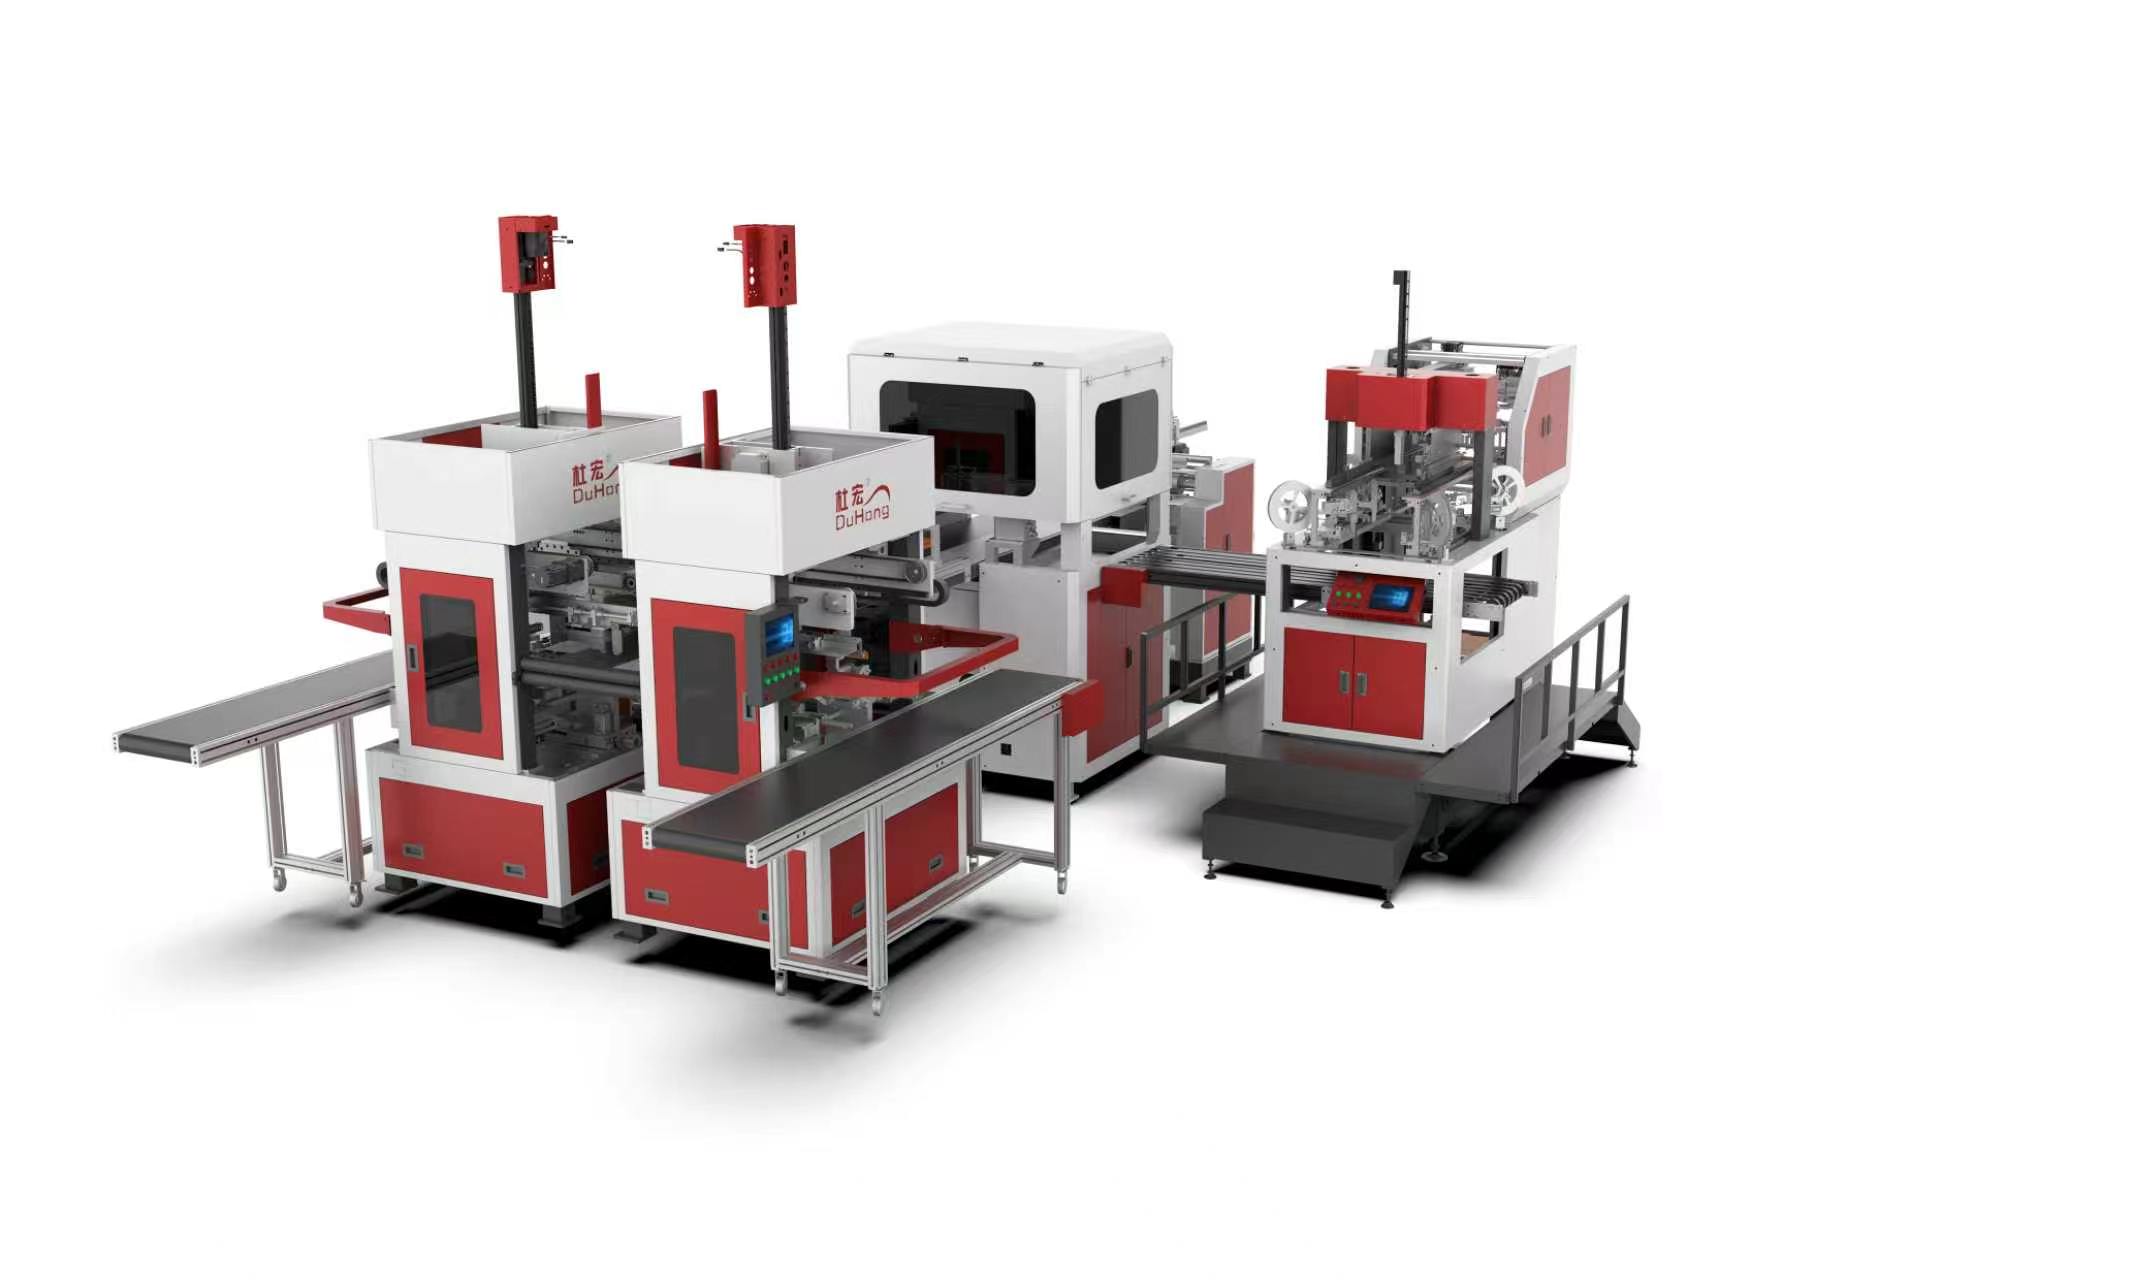
In the wave of automation sweeping across the packaging industry, automatic rigid box equipment has become a core technology supporting high-end packaging for luxury goods, cosmetics, electronics, and other premium sectors. The global market is now experiencing rapid expansion—from manufacturing clusters in China’s Pearl River Delta to precision-oriented European suppliers, from emerging production bases in Southeast Asia to high-end demand centers in North America. Competition in rigid box equipment is intensifying.
However, behind this growth, some manufacturers have begun cutting configurations to reduce cost and grab low-end market share. This “downgrade for price competition” strategy has triggered deep industry reflection: Is cost-cutting a temporary tactic, or a path toward self-destruction?
Based on global data and typical case studies, this report analyzes the essence of downgrading and explores the core logic for sustainable industry development.
I. Global Market Landscape: Growth and Divergence Coexist
The global rigid box automation equipment market now displays clear characteristics of “concentrated leadership and regional divergence.” Technology iteration and demand upgrading are driving market growth while simultaneously giving rise to downgrading behaviors.
(1) Market Expansion With Emerging Economies as Growth Engines
Automation transformation in global packaging is pushing demand for automatic rigid box machines, automatic lid and bottom box machines, and automatic box forming equipment steadily upward.
According to iResearch, China—the world’s key production and consumption hub—reached a market size of RMB 2.86 billion for fully automatic rigid box forming machines in 2022, a YoY increase of 14.3%. The market is expected to exceed RMB 4.5 billion by 2025, with a sustained CAGR of 12%–15%.
Globally, North America and Europe maintain stable high-end demand, while Southeast Asia and the Middle East—benefiting from manufacturing relocation and booming e-commerce—have become new growth centers. China’s exports of rigid box making equipment are expected to exceed USD 800 million in 2025, with Southeast Asia accounting for more than 30%.
Demand segmentation is evident:
-
High-end markets prioritize precision and intelligence—pharma and cosmetics often require positioning accuracy within ±0.1 mm.
Mid- and low-end markets remain highly price-sensitive, leaving temporary survival space for downgraded equipment.
This divergence has caused polarization: companies like Duhong Intelligent focus on technology upgrading, while many Chinese manufacturers fall into the trap of price-driven downgrading.
(2) Competitive Landscape: Solidified Structure and Rising Barriers
The global market is shaped by an “oligopoly-plus-regional-breakthrough” structure. Traditional European rigid box equipment manufacturers continue serving local users relying on legacy technology and convenient after-sales service.
In contrast, China’s Duhong Intelligent builds on past experience and continuously adopts new technologies and structures to break through critical barriers in precision manufacturing and intelligent control. With integrated vision inspection and IoT-based monitoring, Duhong has pushed MTBF beyond 2,000 hours and production speeds past 120 boxes per minute, forming strong competitive barriers.
Many SMEs, however, rely heavily on imported core components and invest insufficiently in R&D (industry average R&D intensity is only 3.4%). Under cost pressure, they often choose to downgrade, sacrificing quality for price—a cycle that deteriorates the overall ecosystem.
II. The Downgrading Dilemma: Short-Term Gains vs. Long-Term Damage
Downgrading is not isolated in the rigid box machinery sector. Its essence is short-termism at the cost of long-term competitiveness.
(1) Main Forms and Root Causes of Downgrading
Typical downgrading takes place in three areas:
-
Core component degradation
Replacing high-precision servomotors with standard motors, reducing 6-axis robotic vision systems to basic sensors—accuracy falls from ±0.1 mm to ±0.2 mm or worse. -
Functional module removal
Eliminating remote diagnostics, predictive maintenance, or intelligent modules, reducing OEE from 85% to below 60%. -
Material downgrading
Using low-grade steel lowers machine durability from 10 years to 3–5 years.
Three pressures drive these behaviors:
-
Cost pressure: Steel price index up 23%; imported servo prices up 12%; manufacturing cost increased 15%–18%.
-
Market pressure: Low-price competition, especially on e-commerce platforms, pushes factory owners to choose downgraded packaging machinery.
-
Competitive pressure: With CR10 at 75%, SMEs are squeezed and resort to price-based survival.
(2) Long-Term Costs Hidden Behind Short-Term Gains
While downgrading may temporarily increase sales volume, long-term damage is extensive.
-
Enterprise Impact
A Pearl River Delta SME reported customer complaint rates rising from 3% to 28% after introducing downgraded automatic rigid box machines, with customer churn reaching 40%.In 2023, Southeast Asia returned more than 200 downgraded rigid box machines due to quality issues, undermining trust in Chinese equipment and hurting compliant suppliers.
-
Industry Impact
Downgrading intensifies price wars, lowering industry margins by 3–5%. Reduced profitability leads to decreased R&D, widening the gap with overseas competitors.
Import dependency remains high—imported high-end box making machines still hold over 25% market share in 2025 projections.
Downstream Market Impact
JD Logistics data shows suppliers using downgraded equipment experienced packaging damage rates rising from 0.8% to 2.3%.
In sensitive fields such as food and pharmaceuticals, poor sealing and dimensional deviation pose safety risks.
III. Breaking the Cycle: Innovation and Value Reconstruction
Leading global companies have proven that the future lies not in “downgrade for cost reduction,” but in “quality-driven efficiency improvement.”
(1) Technology Innovation: From Precision Competition to Intelligent Competition
Leading companies focus R&D on downstream needs to achieve a balance between cost and performance.
Duhong Intelligent consistently uses top-tier components to ensure reliability despite higher manufacturing costs.
Intelligentization is key to efficiency and cost reduction:
-
IoT-enabled machines allow real-time equipment health monitoring
-
Remote diagnostics reduce downtime, saving more than RMB 50,000 per machine annually
-
Duhong’s digital-twin rigid box line reduces delivery lead time by 30% and customer setup cost by 20%
(2) Business Model Upgrade: From Equipment Selling to Service-Driven Value
Leading firms are transitioning into “equipment + service” solution providers.
In 2023, service revenue (remote maintenance, data services, predictive maintenance) accounted for 20% of total revenue and is projected to exceed 30% by 2025.
Duhong Intelligent is developing digitalized full production lines, covering equipment, consumables, and packaging design services—helping clients reduce waste in design and prototyping.
For price-sensitive markets, Duhong adopts standardized and modularized design—without downgrading critical accuracy. Entry-level models reduce cost by 15% through shared components, maintaining reliability while improving competitiveness.
IV. Conclusion: Downgrading Has No Future — Innovation Is the Only Path
The global automatic rigid box equipment industry is at a turning point of technological iteration and market upgrading. Price-driven downgrading is no longer viable in a market increasingly shaped by quality and standards.
By 2023, equipment with intelligent features reached 29% market share, while downgraded products fell from 18% (2021) to 8%. The market has spoken clearly.
The industry’s future requires:
-
Technology-driven cost reduction through domestic core components and intelligent upgrades
-
Model innovation through equipment-plus-service value creation
-
Ecosystem building through collaborative supply chains
The competition in this industry is not about who cuts the most cost—but who delivers the most value.
Downgrading cannot win the present, and it cannot shape the future.
Duhong Intelligent firmly believes: only innovation allows the industry to withstand economic cycles and achieve long-term, stable growth.